A mortgage calculator chart plots the principal and interest portion of every monthly payment across the full life of the loan, so you can see at a glance how much of each payment goes to the bank versus to the loan balance. On a typical 30-year fixed-rate loan, the curve starts steep on the interest side and gradually flattens until the final payment is almost entirely principal. The chart pairs that curve with the running loan balance, which falls slowly at first and accelerates toward the end. Together, those two lines answer the two questions every buyer actually asks: how much will I send the lender every month, and how much of it will ever become equity? Behind every chart is the same standard fixed-rate amortization formula — the monthly payment is calculated once and stays flat for the whole term, while interest and principal portions shift month by month. Once you see the chart, the rest of the loan math stops feeling abstract and starts behaving like a story with a clear shape.
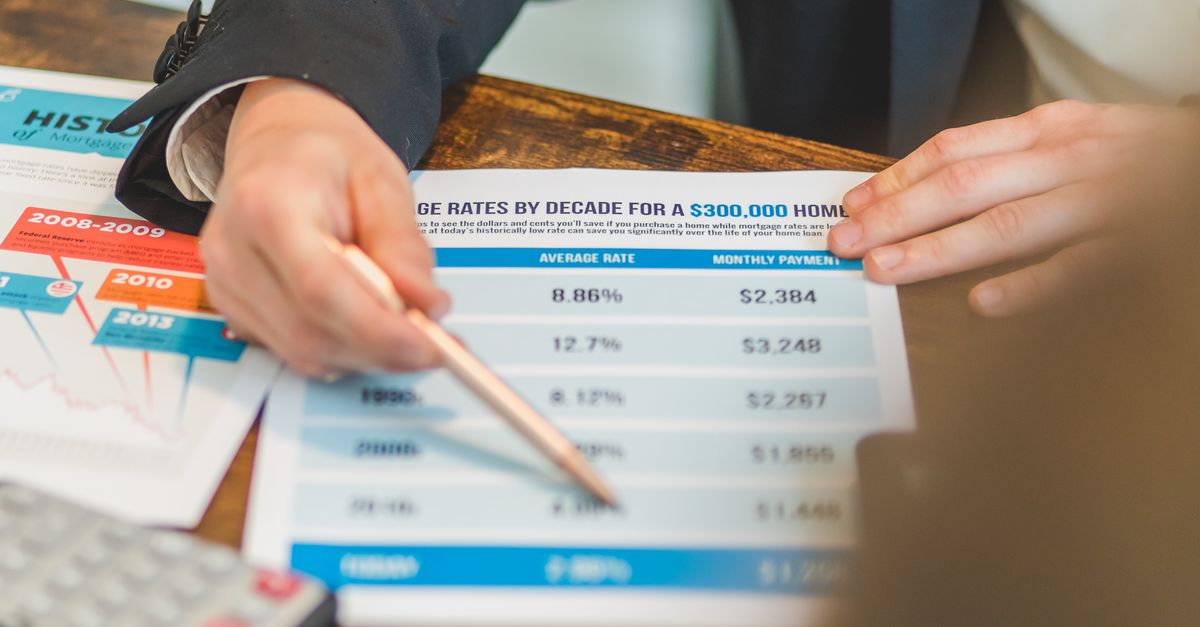
What a Mortgage Calculator Chart Actually Shows
A mortgage chart isn't decoration; it's the visual summary of a single calculation repeated 180 or 360 times in a row. Every row of the underlying amortization table produces one dot or one bar on the chart, and the shape of the chart is determined entirely by four numbers: the loan principal (home price minus down payment), the annual interest rate, the loan term in years, and the assumption that the rate is fixed for the whole term. Once those are set, the monthly principal-and-interest payment is locked, and only the split changes from month to month.
The chart usually shows three pieces of information layered together:
- A curve of the remaining loan balance falling from the original principal to zero by the final payment.
- A stacked bar or stacked area showing, for each year, how much of that year's payments went to interest versus principal.
- A line or table of total interest paid cumulatively, which rises quickly at first and then levels off.
You can think of the chart as a picture of how fast you actually build equity. In the early years, the principal curve barely moves; in the later years, it dives. That asymmetry is not a quirk of any one lender — it is built into the fixed-rate amortization math itself.
Why a Chart View Helps You Budget
A monthly payment number on its own can be misleading. Two loans with identical $1,900 monthly payments can produce wildly different charts, and therefore wildly different equity outcomes, depending on the rate and term. Looking at the chart forces the trade-offs into view.
Three decisions look very different once you see them graphed:
- A 15-year term raises the monthly payment but compresses the chart — interest is paid off far sooner and the balance curve drops sharply after year one.
- A 30-year term flattens the monthly payment but stretches the interest curve out across decades, so a large share of every early payment is interest.
- A rate that is one full percentage point lower can shrink the total interest area on the chart by roughly a quarter to a third, even when the principal and term are unchanged.
The chart also makes refinancing decisions easier. If you already have a loan and are considering a refinance at a lower rate, drawing the new chart next to the old one shows visually how many years of interest you would skip — not just how the monthly payment would change.
Reading the P&I Curve
The headline figure the chart wraps around is the P&I payment — principal and interest only, the amount that repays the loan itself. The standard fixed-rate amortization formula behind it is:
M = P × r × (1 + r)^n / ((1 + r)^n − 1)
where P is the loan principal, r is the monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments (years × 12). When the interest rate is exactly 0%, the formula collapses to M = P ÷ n, an equal split of the principal across every month.
Worked example, with the arithmetic written out:
- Home price $400,000, down payment $80,000 → loan principal P = $320,000.
- Annual rate 6% → monthly rate r = 0.06 / 12 = 0.005.
- Term 30 years → number of payments n = 30 × 12 = 360.
- (1 + r)^n = (1.005)^360 ≈ 6.0226.
- M = 320,000 × 0.005 × 6.0226 / (6.0226 − 1) ≈ $1,918.56 per month.
- Total paid over 360 months = $1,918.56 × 360 = $690,681.60.
- Total interest = $690,681.60 − $320,000 = $370,681.60.
That single monthly figure of $1,918.56 is what the chart's stacked bars are built from. In month one, almost all of it is interest — roughly $1,600 — and only about $318 reduces the principal. By year 15, the split has flipped, and by the final month nearly the entire payment is principal. The chart is just that progression drawn over time.
Generate Your Own Chart in Three Steps
The fastest way to get a chart that matches your own numbers is to use the Mortgage Calculator, which runs the amortization formula and lays out the schedule in your browser without uploading anything.
- Enter the home price and your down payment — the calculator subtracts the down payment to get the loan principal.
- Type your annual interest rate and pick a loan term (15 or 30 years, or enter a custom number of years).
- Read your monthly payment, total interest, and total paid instantly, then expand the amortization schedule or add property tax, insurance, and HOA to see your full PITI monthly total.
Once the three headline numbers appear, the chart is already underneath them — it just needs the amortization rows to be expanded. Each row is one month on the x-axis, and each row's principal and interest columns become the two stacked layers of the chart.
P&I Versus PITI on the Chart
The default chart is a P&I chart: it tracks only the part of your payment that pays down the loan. Real housing costs are usually larger, because property taxes, homeowners insurance, and HOA dues are paid alongside the loan. When you add those three optional fields, the calculator also shows an estimated monthly total commonly called PITI (Principal, Interest, Taxes, and Insurance), plus HOA if applicable.
The way the tool estimates each component is straightforward:
| Component | How the calculator estimates it |
|---|---|
| Property tax (monthly) | Home value × annual tax rate ÷ 12 |
| Homeowners insurance (monthly) | Annual premium ÷ 12 |
| HOA dues (monthly) | Entered as a flat monthly amount |
| P&I (monthly) | Standard amortization formula on P, r, n |
| PITI + HOA (monthly) | P&I + property tax + insurance + HOA |
These add-ons do not change the chart's P&I curve, because they don't pay down the loan. They only raise the cash you send each month, which is why lenders qualify borrowers on PITI rather than P&I alone — they want to know whether the full monthly outflow fits the household budget, not just whether the loan amortizes.
What a Mortgage Chart Does Not Include
The standard fixed-rate amortization formula assumes a constant rate and monthly compounding for the full term. Several real-world cost components are deliberately left out of the chart because they depend on facts the calculator doesn't have.
- Private mortgage insurance (PMI). Usually required when the down payment is below 20%; the chart does not add it automatically.
- Discount points and origination fees. Paid up front at closing; they change the effective rate but not the headline rate you typed in.
- Closing costs. Paid once at closing, not monthly, and therefore not visible on a monthly chart.
- Adjustable-rate resets. If your loan is an ARM, the rate after the introductory period will change the chart's shape, which a fixed-rate calculator cannot show.
- Escrow adjustments. Property tax and insurance estimates can be revised once a year, so the PITI line on the chart is an estimate, not a locked figure.
- Extra payments. Any additional principal you pay shortens the schedule and reshapes the chart; the standard formula assumes you only make the minimum payment.
When to Verify the Numbers With a Lender
The chart is a planning tool, not a loan offer. It uses the same formula U.S. lenders use to quote fixed-rate mortgages, and it is accurate to within rounding for any standard fixed-rate loan — but the final numbers on a real Loan Estimate come from the lender's own systems, including your credit score, the property's appraisal, the loan-to-value ratio, and any points or credits specific to that transaction. For any decision that commits money, confirm the figures with a licensed lender or mortgage professional before signing.
If you want to dig into the math behind the chart in more depth — including the year-by-year schedule that powers it — see how to calculate mortgage payments, interest, and PITI, which walks through the same formula with extra worked examples. For the broader reference, the Wikipedia mortgage calculator entry documents the standard amortization assumptions in detail.
For a deeper look, see Tip Calculator Chart: Bills, Tips, and Totals at a Glance.